How to Lower High-Risk Car Insurance After SR-22 in 2026: A Step-by-Step Recovery Plan
- An SR-22 is a form your insurer files with the state — it is not a separate insurance policy.
- Expect a one-time filing fee (often $15–$50) plus a premium increase that reflects the underlying violation.
- You must keep the policy continuous for the state's full requirement period, usually 1–3 years.
Introduction: SR-22 Ends — But High-Risk Rates Don’t Disappear Overnight
Many drivers assume the moment their SR-22 requirement ends, their premiums will instantly return to normal.
That’s rarely how underwriting works.
An SR-22 filing is just proof of financial responsibility.
The violation behind it — especially a DUI — can stay on your driving record for 3 to 10 years depending on your state.
The good news?
Insurance pricing follows predictable recovery patterns. If you understand how insurers calculate risk, you can actively accelerate your return to standard-tier pricing.
This guide gives you:
- A 12–36 month recovery roadmap
- Cost-reduction strategies that actually move underwriting tiers
- Credit-based insurance score optimization
- Policy restructuring tactics
- Long-term financial recovery planning
SR-22 is temporary.
High-risk pricing does not have to be permanent.
Why Insurance Stays Expensive After SR-22
The filing disappears.
The violation does not.
Insurance companies base pricing on:
- Historical claim probability
- Severity modeling
- Violation recency
- Credit-based insurance scoring (in most states)
- Continuous coverage history
For example:
A DUI from 3 years ago may still carry a 40–80% surcharge in many rating models — even if SR-22 is removed.
That’s why recovery is structured, not automatic.
Step 1: Confirm SR-22 Removal Properly
Before making changes:
- Confirm your required filing period is complete
- Verify DMV compliance is satisfied
- Request your insurer remove the SR-22 endorsement
- Get written confirmation
Do NOT cancel your policy prematurely.
A coverage gap—even one day—can reset your risk tier and increase premiums further.
Step 2: Re-Shop Immediately After Filing Removal
Many drivers stay with the same carrier out of inertia.
That’s often expensive.
Once SR-22 is removed, you may qualify for:
- Standard carriers like GEICO
- Tier-shift pricing with Progressive
- Re-entry underwriting with State Farm
Each company evaluates violation age differently.
Typical Rate Shift After SR-22 Removal
| Scenario | Estimated Premium Change |
|---|---|
| Minor violation | -10% to -20% |
| DUI (Year 3–4) | -5% to -15% |
| Multiple violations | Minimal immediate change |
Shop within 30 days of filing removal.
That window matters.
Step 3: Improve Your Insurance Credit Score
In most states, insurers use a credit-based insurance score (not identical to FICO).
Improving financial behavior can reduce premiums significantly.
High-Impact Actions
Pay down revolving credit utilization below 30%
Avoid late payments
Avoid unnecessary hard inquiries
Keep older accounts open
Insurance scoring weighs stability heavily.
Small credit improvements can produce 5–20% premium shifts over 12 months.
Step 4: Optimize Coverage Strategically
Now is the time to restructure — carefully.
Adjustments That Often Save
| Adjustment | Potential Savings |
|---|---|
| Raise deductible from $500 to $1,000 | 5–10% |
| Remove rental reimbursement | 2–5% |
| Bundle renters/home | 5–15% |
| Reduce unnecessary comprehensive on low-value car | 5–12% |
Be strategic, not reckless.
Don’t underinsure just to chase short-term savings.
Step 5: Understand the Real Recovery Timeline
High-risk pricing decays over time.
DUI Premium Recovery Pattern
| Years Since Violation | Typical Impact |
|---|---|
| Year 1 | Highest surcharge |
| Year 2 | Slight decline |
| Year 3 | Moderate reduction |
| Year 4–5 | Major improvement |
| Year 6+ | Near standard tier (state dependent) |
Avoid even minor tickets during this window.
One speeding citation can delay recovery by 12–24 months.
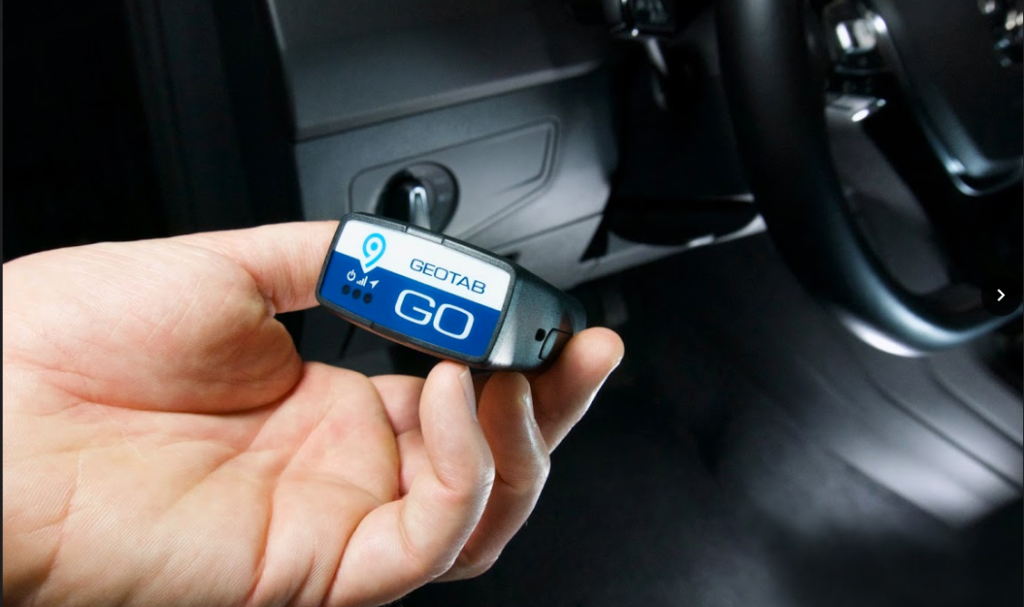
Step 6: Use Telematics to Accelerate Trust
Usage-based programs from companies like Allstate and Nationwide track:
- Braking patterns
- Mileage
- Night driving
- Speed consistency
Safe driving scores can unlock:
5%–30% discounts.
For recovering drivers, this is one of the fastest measurable discount tools available.
Step 7: Vehicle Optimization Strategy
Your car choice impacts pricing more than most realize.
Premium drivers often overlook:
- Theft frequency
- Repair cost index
- Safety rating
- Performance classification
Switching from a sports coupe to a mid-size sedan can reduce premiums 15–35%.
During recovery years, practicality beats prestige.
Step 8: Avoid Coverage Gaps at All Costs
Continuous insurance history is one of the strongest rating factors.
Even after SR-22 ends:
A lapse can:
- Increase future quotes
- Trigger underwriting review
- Reclassify you as higher-risk
Auto insurance pricing rewards stability.
Protect your continuity record.
Step 9: Payment Structure Matters
Installment fees are hidden costs.
Annual Cost Comparison
| Payment Method | Extra Annual Cost |
|---|---|
| Monthly | $60–$180 |
| 6-Month | $0–$60 |
| Annual | Lowest total |
If financially possible, reduce installment frequency.
It compounds over years.
Step 10: Re-Shop Every 12 Months
Even if your record doesn’t change:
- Insurer risk appetite changes
- State regulations shift
- Competition alters pricing
Annual re-shopping is mandatory during recovery years.
Loyalty rarely equals lowest price.
Psychological & Financial Recovery
High-risk classification creates:
- Financial pressure
- Stress
- Driving anxiety
Track recovery intentionally:
Year 1 premium vs Year 3 premium
Year 3 vs Year 5
Progress becomes motivating when measured.
SR-22 recovery is gradual — but predictable.
If Rates Don’t Drop After 3–4 Years
Take investigative steps:
- Request your CLUE report
- Review driving record accuracy
- Dispute incorrect violations
- Consult independent agents
Incorrect claims history can artificially inflate pricing.
Data errors are more common than drivers expect.
Long-Term Financial Impact Example
DUI requiring 3-year SR-22:
| Period | Estimated Premium |
|---|---|
| Years 1–3 | $9,000 |
| Years 4–5 | $6,500 |
| Years 6–7 | $5,000 |
Total 7-year cost: $20,500+
With structured recovery actions, you can reduce that by several thousand dollars.
Advanced Strategy: Multi-Policy Positioning
After Year 3:
Consider:
- Adding renters insurance
- Adding umbrella coverage
- Increasing liability limits
Why?
Some carriers move clients into preferred tiers when total relationship value increases.
It’s counterintuitive — but sometimes spending slightly more strategically lowers overall cost.
Final Thoughts
SR-22 compliance is Phase One.
Financial rehabilitation is Phase Two.
Lowering high-risk insurance after SR-22 requires:
- Smart shopping
- Credit discipline
- Clean driving
- Coverage optimization
- Patience
Premiums rarely drop overnight.
But consistent action over 24–36 months produces measurable results.
Your record improves.
Your risk tier improves.
Your financial stability improves.
SR-22 may define a chapter — not your entire driving future.